Proactive Tax Planning Strategies to Lower Your Bill in North Carolina (2025 Guide)
High-income professionals, business owners, retirees, and families in NC benefit most when tax planning is coordinated year-round and integrated with retirement, investment, and estate strategies. This guide explains how tax planning works, what strategies are available in 2025, and how North Carolina tax rules affect your plan.
How to Choose the Right Financial Advisor for Your Situation
Major life changes—such as retirement, divorce, receiving an inheritance, selling a business, or navigating a career transition—often bring with them a mix of opportunity and uncertainty. These moments can reshape your financial landscape in ways that are both deeply personal and financially significant. While some individuals may feel comfortable managing certain aspects of their finances on their own, many reach a point where professional guidance becomes essential for making informed, well-structured decisions.
Tax-Smart Ways to Transfer Business Ownership
Transferring ownership of a business is more than a financial transaction—it’s a decision that affects employees, customers, family members, and future legacy. The way the transition is structured can significantly influence how much of the proceeds an owner keeps after taxes. Planning ahead, understanding available strategies, and coordinating advisors can help support a smoother, more intentional transition process.
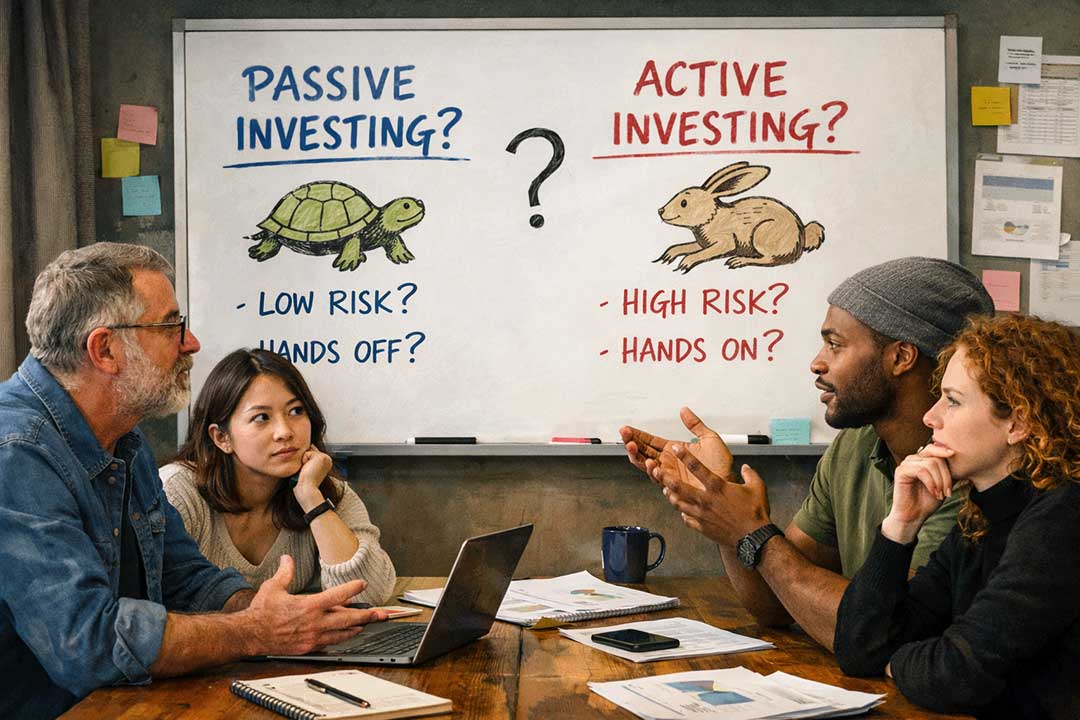
Active vs. Passive Investing: Which Is Right for You?
For decades, the question of active vs. passive investing has shaped how individuals, institutions, and financial professionals think about building long-term portfolios. While the tools, products, and technology surrounding investing have evolved, the central debate remains the same: Is it better to follow a rules-based, low-cost index approach, or to pursue a research-driven strategy that attempts to outperform the market?
How Fees and Transparency Build Long-Term Trust
Financial advice is built on trust. Whether someone is a working professional, a business owner, a high-net-worth individual, or approaching retirement, the relationship with a financial advisor often spans decades and involves deeply personal financial decisions. At the center of that relationship lies a critical but frequently misunderstood issue: how the advisor is paid and how clearly those costs are disclosed.
Why Business Owners Need a Wealth Continuity Plan
Business owners often carry two roles at once: they run the company day-to-day, and they are the primary stewards of the family’s long-term financial security. Because so much personal wealth is tied to the business, even a brief disruption—let alone an unexpected transition—can have immediate financial consequences. This is where a wealth continuity plan becomes essential.
How a Financial Plan Differs from an Investment Portfolio
When people think about their finances, one thing that often comes to mind is investing — choosing stocks, funds, or other assets in hopes of growing wealth over time. As a result, terms like investment portfolio, investment plan, and financial planning are frequently used interchangeably. In reality, however, a financial plan and an investment portfolio are not the same thing, even though they are closely connected.
Widowed? Steps to Take in the First 90 Days
Losing a spouse alters every part of life—emotionally, practically, and financially. Even when the loss is expected, the first weeks often feel disorienting. Many people describe this period as a “fog,” where routine tasks suddenly feel unfamiliar and decisions take more effort than usual. This is a normal part of grieving, and it’s one reason why the first 90 days after widowhood benefit from a clear, steady framework rather than urgent, high-pressure decisions.
The Role of an Advisor During a Liquidity Event
Selling a business, recapitalizing, bringing in outside investors, or transitioning ownership can create one of the most important financial turning points in a business owner’s life. A liquidity event can change how your wealth is structured, how your taxes are managed, how your family plans for the future, and how much risk you carry after the transaction.
Creating a Financial Plan for Life After Selling Your Business
Selling a business is a meaningful milestone. It reflects years of decisions, leadership, and personal commitment. Once the sale is complete and the ownership transition is behind you, the financial landscape changes quickly. What was once business equity—dynamic and tied to operations—may now be liquidity that requires thoughtful long-term planning.